Română
 Русский
ACCOUNTING AND TAXATION OF LEASING CONTRACTS
PART 2
Sxomple 2.
On 10.05.201X, the “Alfa” entity leased a car to the “Beta” entity for a period of 36 months. According to the contract, after the expiration of the leasing term, on 09.05.201X+3, the car becomes the property of the lessee. The entry value of the car is equal to the refundable value and is 34 152 EUR, recalculated at the NBM exchange rate on 10.05.201X 1 EUR = 18.6839 lei, which is 638 092.55 lei. The refundable amount in lei is reflected in the WH 0675647 invoice dated 10.05.201X.
The leasing interest is 9% of the unpaid redeemable value of the asset and is paid monthly until the 10th. At the beginning of the leasing term, the lessee pays an advance in the amount of 10% of the reimbursable value and amounts to 63 809.26 lei. The advance will be taken into account when paying the debt to the lessor starting with the 30th month.
According to the contractual provisions, the amount of monthly lesing payments is EUR 759.10 and will be paid at the commercial rate of BC “Victoriabank” SA from the date of payment. On 10.06.201X the principal was calculated in the amount of 581.79 EUR and the leasing interest – 177.31 EUR. The commercial exchange rate at the date of payment was EUR 19.00.
The depreciation of the car is calculated according to the linear method, the annual depreciation norm being 12.5%. The car will be used by the sales department.
Upon receipt of the leased car, the lessee incurred the following expenses: one-time commission paid to the lessor in the amount of EUR 683.04, the equivalent of MDL 12 761.85;
CASCO insurance premium for the first year – EUR 1,536.84, the equivalent of RON 28,714.16; mandatory insurance premium for 201X – 1 920 lei; expenses related to the registration and registration of the car – 1 150 lei.
According to the accounting policy, the above-mentioned expenses are considered insignificant.
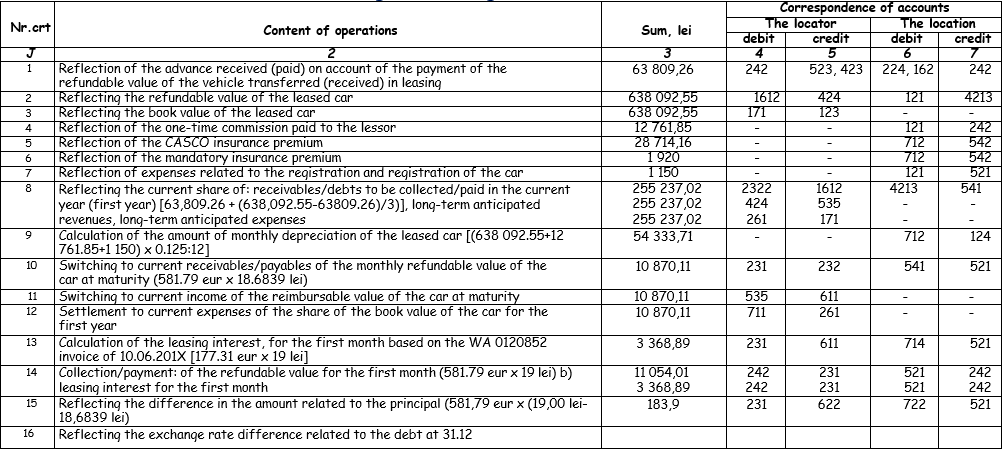
It is required by: prepared the accounting formulas and calculations related to the leasing of the car to the lessee and lessor.
Based on the data in the example, the lessor and the lessee will account for the economic operations in the following way:
Financial leasing accounting records