Română
 Русский
ACCOUNTING AND TAXATION OF LEASING CONTRACTS
PART 2
According to NAS Exchange rate and amount differences,
pct.5. Foreign currency operations include:
According to the NAS Exchange Rate and Amount Differences, the manner of documenting the exchange rate differences related to operations in foreign currency with residents of the Republic of Moldova is conditioned by the date of recalculation in national currency of assets and receivables in foreign currency.
The exchange rate differences recorded at the date of payment of receivables and debts must be documented in the same way as the transactions carried out with non-residents, i.e. on the basis of payment documents (payment orders, account statements).
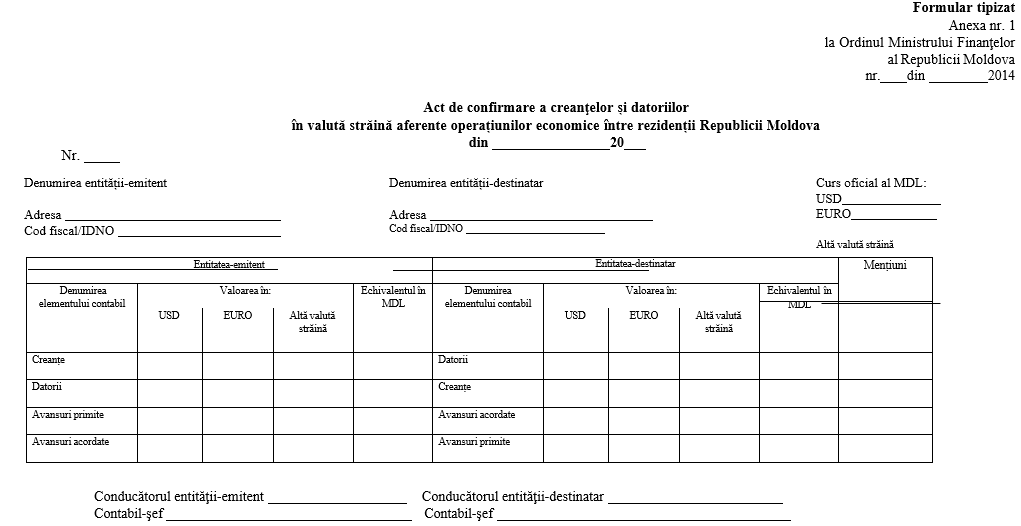
The exchange rate differences calculated at the reporting date must be confirmed by the standard primary document “Act of confirmation of receivables and liabilities in foreign currency related to economic operations between residents of the Republic of Moldova” (hereinafter – act of confirmation of receivables and liabilities in foreign currency).
The form of the nominated act and the instruction on how to fill it in are approved by the Order of the Minister of Finance no. 71 of 30.05.2014 (no. 153–159/ 13.06.2014).