Română
 Русский
ACCOUNTING AND TAXATION OF LEASING CONTRACTS
PART 2
Accounting of the operating lease to the lessee
The assets received in operational leasing are reflected by the lessee in the off-balance sheet accounts at the value agreed by the parties in the leasing contract (item 26).
The direct costs related to the entry (return) of the leased asset and the maintenance costs, which according to the terms of the contract are borne by the lessee, are recorded as current costs or expenses depending on the destination and place of use of the respective asset.
If these costs exceed the predetermined materiality threshold and refer to two or more management periods, they can be reflected in the composition of the anticipated expenses with the subsequent settlement of current expenses in the manner provided by the lessee’s accounting policy (item 27).
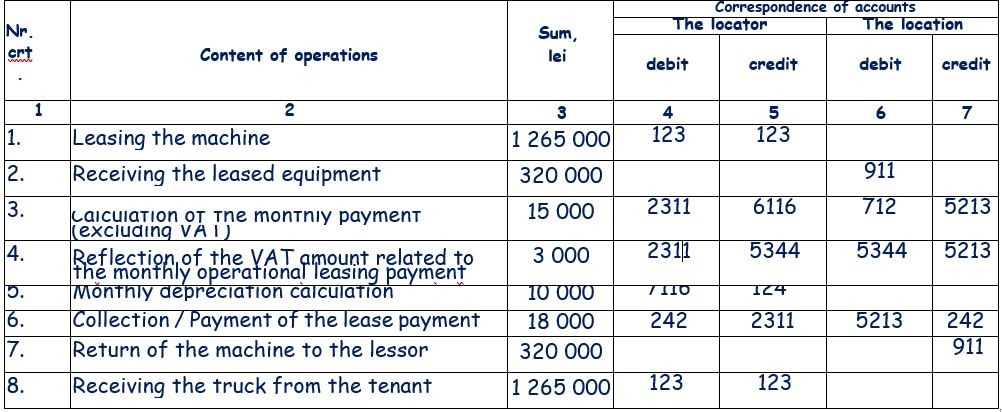
Sxomple J. In May 201X, entity “A” transferred a truck to entity “B” on an operational lease for a period of 2 years.
According to the leasing contract, the guaranteed residual value is 320 000 lei. The entry cost of the truck is 1 265 000 lei, the residual value – 65 000 lei.
The depreciation is calculated by the linear method according to the annual norm of 10%. The monthly leasing payments amount to 18 000 lei, including VAT.
The truck is used for the purpose of distributing products.
To prepare the accounting formulas and calculations related to the leasing of the truck to the lessee and lessor.
Accounting records regarding operating leasing according to NAS