Română
 Русский
ACCOUNTING AND TAXATION OF LEASING CONTRACTS
PART 3
Sxomple 7:
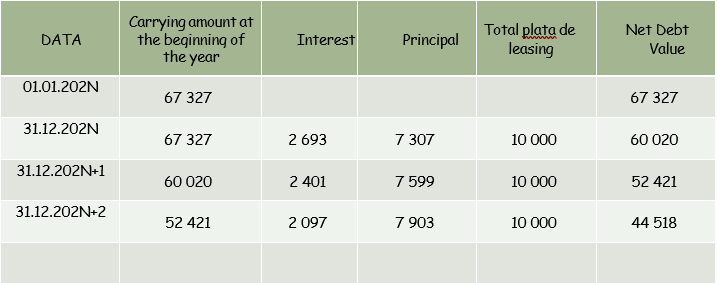
On 01.01.202N, Interfobos SRL, lessee, concluded a lease contract for a production equipment for a period of 4 years.
The annual leasing payments amount to MDL 10,000 and are paid at the end of each year. The default rate of the contract is 4%. The direct initial costs of the leasing contract amount to MDL 1,000.
The contract is quietly extended only once under the same conditions, unless the lessee terminates the contract with 6 months’ notice. Interfobos SRL is very dependent on this machine and is very unlikely to resort to termination.
According to the company’s accounting principles, the machines are depreciated over 7 years.
(PV, K4 = 6,732745)
Dt Right to use the asset under the leasing contract 68 327,45 MDL
Ct Preliminary lease debt 67 327,45 MDL
Ct Current payables 1 000,00 MDL
Depreciation of the right of use 68 327,45 / 7 Years = 9 761,06 MDL
Dt Expenses/costs with the amortization of the right of use
Ct Depreciation of the right of use