

 Română
 Русский
ACCOUNTING AND TAXATION OF LEASING CONTRACTS
PART 3
Sxomple 3:
An entity enters into a leasing contract for a period of 7 years for the use of industrial equipment. Annual fixed rate: 100 000 lei. Marginal loan rate applied: 3%.
The table below represents the schedule received from the lessor, which is also a supporting document for the lessor, based on which the lessee will separate the right of use and the interest.
From the calculation below, it follows:
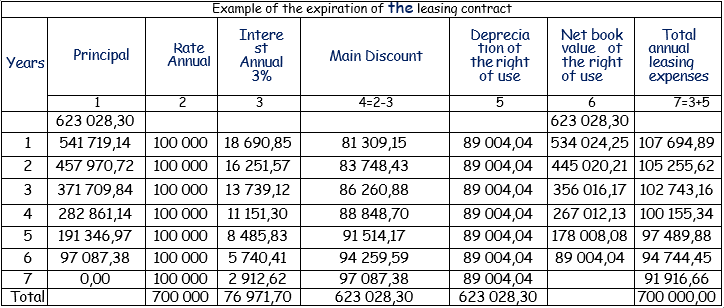
Based on the above example, the principal reflection of the operations in the lessee’s accounting, according to the provisions of IFRS, is as follows:
Recognition of the leasing right in the accounting. This right can be recognized in the form of an intangible asset, in correspondence with the leasing debt, at the remaining value of the payments, updated according to the interest rate used: MDL 623 028.30.
Dt Right to use the asset under the leasing contrac
Ct Preliminary Lease Debt
Dt Interest expenses
Ct Preliminary lease debt
Based on the above example, the principle reflection of the operations in the lessee’s accounting, according to the provisions of IFRS, is as follows:
Dt Preliminary lease debt
Ct Lesing Debts
Dt Expenses/costs with depreciation of the right of use
Ct Depreciation of the right of use
Regarding the subsequent valuation, after the start date of the development, a lessee must value the asset related to the right of use applying the cost-based model.