

 Română
 Русский
ACCOUNTING AND TAXATION OF LEASING CONTRACTS
PART 3
Sxomple 4:
An entity concludes a 3-year leasing contract for the use of a car, starting with 01.01.202N (with the possibility of terminating the leasing contract before the expiry date). Annual fixed rate: 15 000 MDL. Marginal loan rate applied: 6%.
The entity has the right to purchase the car at the end of the leasing contract for 80,000 MDL. The expected fair value at the end of the lease agreement is MDL 130,000. DFU = 5 years, calculation of depreciation according to the linear method. From the calculation below, it follows:
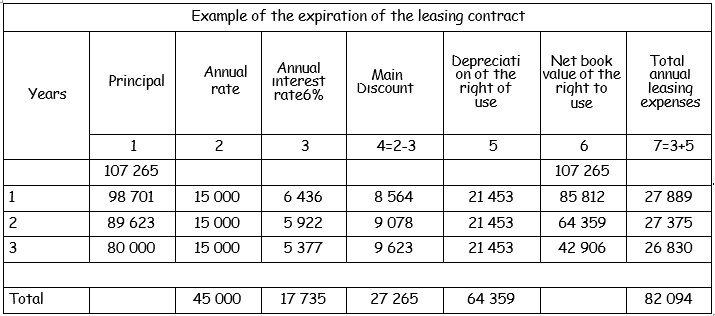
Based on the above example, the principled reflection of the operations in the lessee’s accounting, according to the provisions of IFRS, on 01.01.202N:
Dt Right to use the asset under the leasing contract
Ct Preliminary Lease Debt and 31.12.202N+2:
Dt Interest expenses
Ct Preliminary Lease Debt
Dt Preliminary lease debt
Ct Debts concerning lesing
Dt Expenses/costs with the amortization of the right of use
Ct Depreciation of the right of use
Dt Fixed assets
Ct Right to use the asset under the leasing contract
Dt Preliminary lease debt
Ct Cash